The Post-Midterm Reset: Crude Drops, Safe Havens Pop
By Fauzia Timberlake, personal coach for trading options
November 2, 2026
Macro Overview of Markets
Capital market dynamics for the week of November 2–6th were primarily governed by a macro regime shift following the U.S. midterm elections, alongside mixed economic prints and post-earnings Tech valuation adjustments. The defining catalyst driving cross-asset flows was a sharp re-pricing in commodity markets–led by a steep drop in WTI Crude Oil—coupled with a flight to safety that boosted precious metals and altered interest-rate expectations ahead of the Fed's upcoming policy decisions.
Equity benchmarks experienced volatile two-way trading throughout the week. High-beta technology and semiconductor names faced persistent valuation drag and earnings-related profit-taking, while defensive sectors absorbed safety inflows. Despite a late-week attempt at stabilization, benchmark indices ended under moderate pressure.
(S&P 500 Friday Close: 7,376.86)
Fixed-income markets saw modest yield compression early in the week as flight-to-quality buying emerged, before stabilizing on Friday following the monthly employment report. Treasury yields remained range-bound near multi-month highs as market participants calibrated rate-cut trajectories for December.
(10-Year Treasury Yield Close: 4.86%)
Crude oil suffered a major tactical unwinding, tumbling over 12% across the week. Growing global demand concerns and substantial inventory builds triggered heavy unwinding of risk premiums, sending prices down to test multi-week support before finding late-week buyers.
(Crude Oil Close: $90.83 / bbl)
Spot gold benefited significantly from macro uncertainty and geopolitical hedging, breaking firmly above key psychological thresholds midweek. Strong safe-haven demand shielded the metal from broader market liquidation, despite light profit-taking into Friday's close.
(Gold Close: $4,074.90 / oz)
Cryptocurrencies traded largely in lockstep with broader growth-risk sentiment. Bitcoin experienced minor selling pressure early in the session before consolidating around key support levels to close out the week.
(BTC/USD Friday Close: $75,731.04)
Strategy Corner
Based on last week's market movements, here are some trading ideas and option strategies for the readers' consideration. The positions can be scaled bigger (or smaller) to suit individual account size.
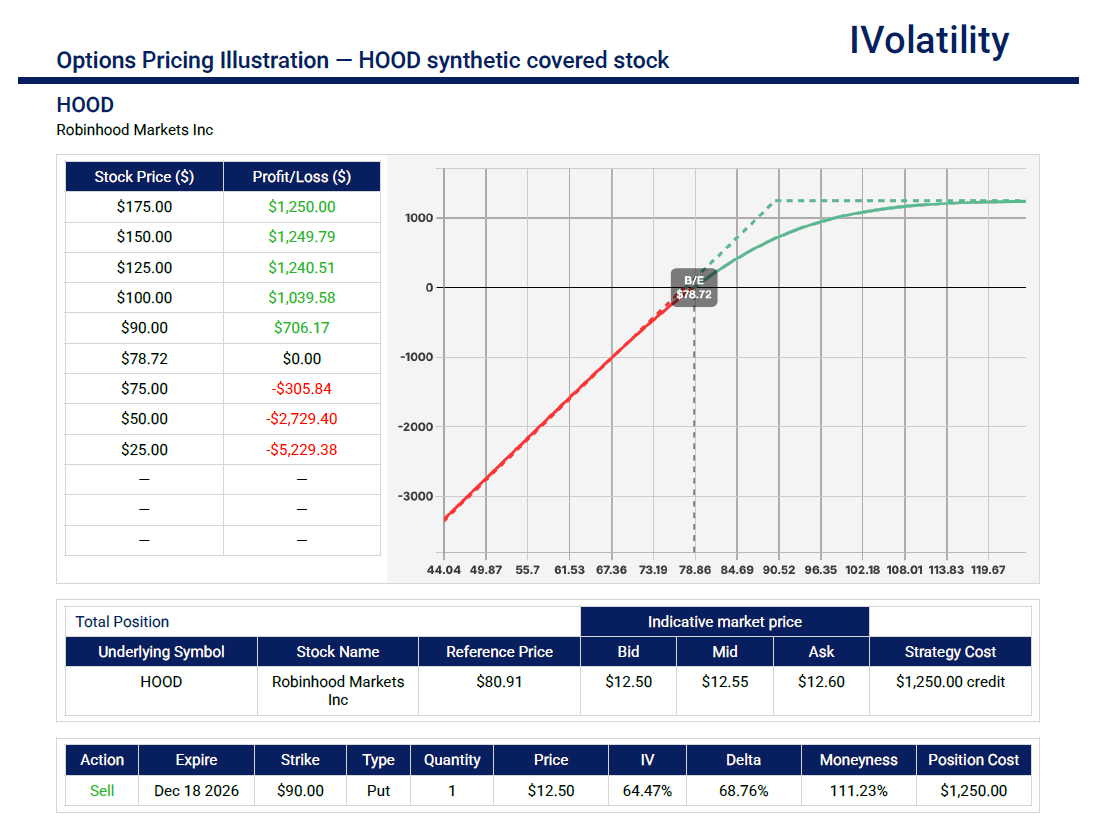
HOOD (closed around 80.90 on Friday, Nov 6th)
If a trader believes that the recent tech-wide sector choppiness may be subsiding, then getting bullish in HOOD could be a reasonable position. Selling an in-the-money put creates a high-delta, bullish position designed to capture both substantial intrinsic value and elevated implied volatility decay as the stock stabilizes following recent declines.
- Structure: synthetic covered stock
- Position: In the December monthly expiration, sell the ITM 90put
- Probability of Profit of about 55%
- Credit collected about $1250/contract
- Breakevens at around 78 (just below where the stock closed on Friday)
SPX (closed around 7376.86 on Friday, Nov 6th)
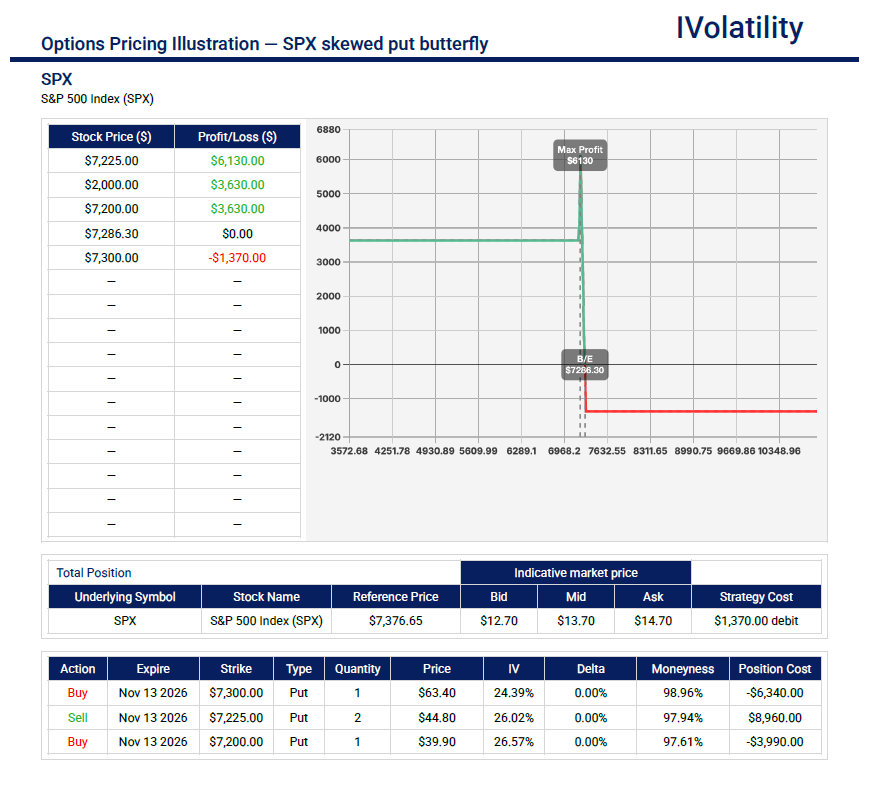
If a trader anticipates that markets might continue to be disturbed for a few weeks, a hedge could be employed using a skewed put butterfly. By paying a modest additional net debit relative to a standard symmetrical butterfly, this position is structured so that the long put leg's value offsets or exceeds the net debit paid if SPX suffers a catastrophic sell-off—effectively eliminating downside risk below the lower strikes while capturing maximum profitability inside the expected downside volatility zone.
- Structure: skewed put butterfly
- Position: In the Nov 13th expiration, buy one 7300put / sell two 7225puts / buy one 7200put
- Total cost of about $1375
- Maximum potential profit $6125 (7500 - 1375) if SPX pins 7225 at expiration
- No risk to the downside and upside risk is limited to debit paid for the butterfly
- The strikes can be adjusted to suit account size as long as the characteristic of the skewed butterfly is maintained (near wing span should exceed far wing span)
Movement of the Major Market Indices:
| INDEX | UP | DOWN |
| SPY | -2.18% | |
| QQQ | -5.64% | |
| IWM | -3.12% | |
| DIA | -1.86% | |
| GLD | 2.65% | |
| BTC/USD | -3.27% | |
| 10-year yield | -0.41% | |
| Crude Oil | -12.32% | |
| VIX | 18.45% |
Movement of the Major Market Sectors:
| SECTOR | UP | DOWN |
| TECH (XLK) | -5.64% | |
| FINANCIALS (XL) | -1.84% | |
| INDUSTRIALS (XLI) | -1.62% | |
| ENERGY XLE | -12.32 | |
| HEALTHCARE (XLV) | -1.45% | |
| UTILITIES (XLU) | -0.78% | |
| MATERIALS (XLB) | -2.15% | |
| REAL ESTATE (XLRE) | -1.08% | |
| CONSUMER STAPLES (XLP) | 0.42% | |
| CONSUMER DISCRETIONARY (XLY) | -3.58% |
Notable Gainers Week of Nov 2nd – 6th
Despite broad-based choppiness and defensive rotation across major benchmark indices, selective upside momentum emerged in corporate earnings beats, strategic merger announcements, and high-growth consumer/technology turnarounds.
Outperformers were led by biotech regulatory catalysts, strong quarterly earnings beats accompanied by upgraded revenue guidance, and corporate M&A transactions. High-volume names with daily liquidities exceeding one million shares attracted significant institutional dip-buying, separating themselves from the broader market pullback.
- Inovio Pharmaceuticals, Inc. (INO) (+213.75%): Shares surged following a regulatory catalyst after receiving FDA Accelerated Approval for its RRP immunotherapy treatment, triggering heavy short-covering and speculative buying.
- EVgo Inc. (EVGO) (+46.83%): The electric vehicle charging network provider jumped following strategic M&A announcement updates and expansion partnerships.
- Krispy Kreme, Inc. (DNUT) (+30.68%): The sweet treat chain posted a sharp advance after delivering a third-quarter earnings beat, raising full-year revenue guidance, and citing operational turnaround progress.
- Portillo's Inc. (PTLO) (+28.81%): Shares climbed significantly following better-than-expected quarterly results and positive store expansion metrics.
- Aehr Test Systems (AEHR) (+26.50%): The semiconductor test equipment supplier rallied after reporting strong fiscal first-quarter revenue growth and raising its full-year sales outlook threefold.
- ADMA Biologics, Inc. (ADMA) (+26.05%): The commercial biopharmaceutical company traded up sharply after reporting strong quarterly revenue growth and expanding operating margins.
- Airbnb, Inc. (ABNB) (+11.67%): The travel booking giant gained ground following robust international travel demand metrics and strong free-cash-flow performance in its quarterly release.
- Shopify Inc. (SHOP) (+3.59%): The e-commerce platform provider bucked technology sector pressure, advancing on strong merchant solutions growth and positive holiday quarter outlooks.
Notable Losers Week of Nov 2nd – 6th
Equity markets faced broad-based selling pressure throughout the week, with downside concentrated heavily in technology, semiconductor infrastructure, and energy sectors. Heightened volatility stemmed from a combination of macro headwinds—including pre-election positioning, post-earnings reactions, and shifting rate-cut expectations—alongside a sharp pullback in Crude Oil prices, which triggered a 12.32% weekly drop in the energy sector. High-beta growth names and tech infrastructure suppliers were hit particularly hard as investors rotated into defensive assets ahead of key economic data releases.
- Cogent Communications Holdings Inc. (CCOI) (-41.16%): Shares plummeted after the telecommunications and data facility provider issued weaker-than-expected quarterly results, alongside growing concerns regarding capital expenditure expansion costs.
- Lumentum Holdings Inc. (LITE) (-35.96%): The optical networking and photonics manufacturer slid significantly following its quarterly earnings release and conservative forward guidance, alongside an all-stock merger deal that disappointed investors expecting stronger immediate AI telecom demand.
- Stevanato Group S.p.A. (STVN) (-29.98%): The drug containment and delivery solutions maker dropped steeply after missing quarterly revenue estimates and cutting full-year revenue and margin outlooks.
- Seagate Technology Holdings plc (STX) (-28.43%): Storage hardware supplier Seagate stumbled amid heavy profit-taking across memory and data infrastructure providers as broader semiconductor demand sentiment turned cautious.
- Marvell Technology, Inc. (MRVL) (-28.12%): The semiconductor giant surrendered recent gains amid a sector-wide chip sell-off, further amplified by strategic merger announcements and broader volatility across AI-adjacent hardware names.
- Halozyme Therapeutics, Inc. (HALO) (-15.72%): Shares fell following analyst downgrades and revised price target reductions tied to long-term royalty structure expectations.
- Natera, Inc. (NTRA) (-14.59%): The cell-free DNA testing company traded down as executive transition announcements sparked temporary uncertainty among institutional investors.
- Globus Medical, Inc. (GMED) (-13.08%): The musculoskeletal solutions manufacturer declined following a third-quarter revenue miss and cautious broker commentary regarding near-term hospital capital spending.
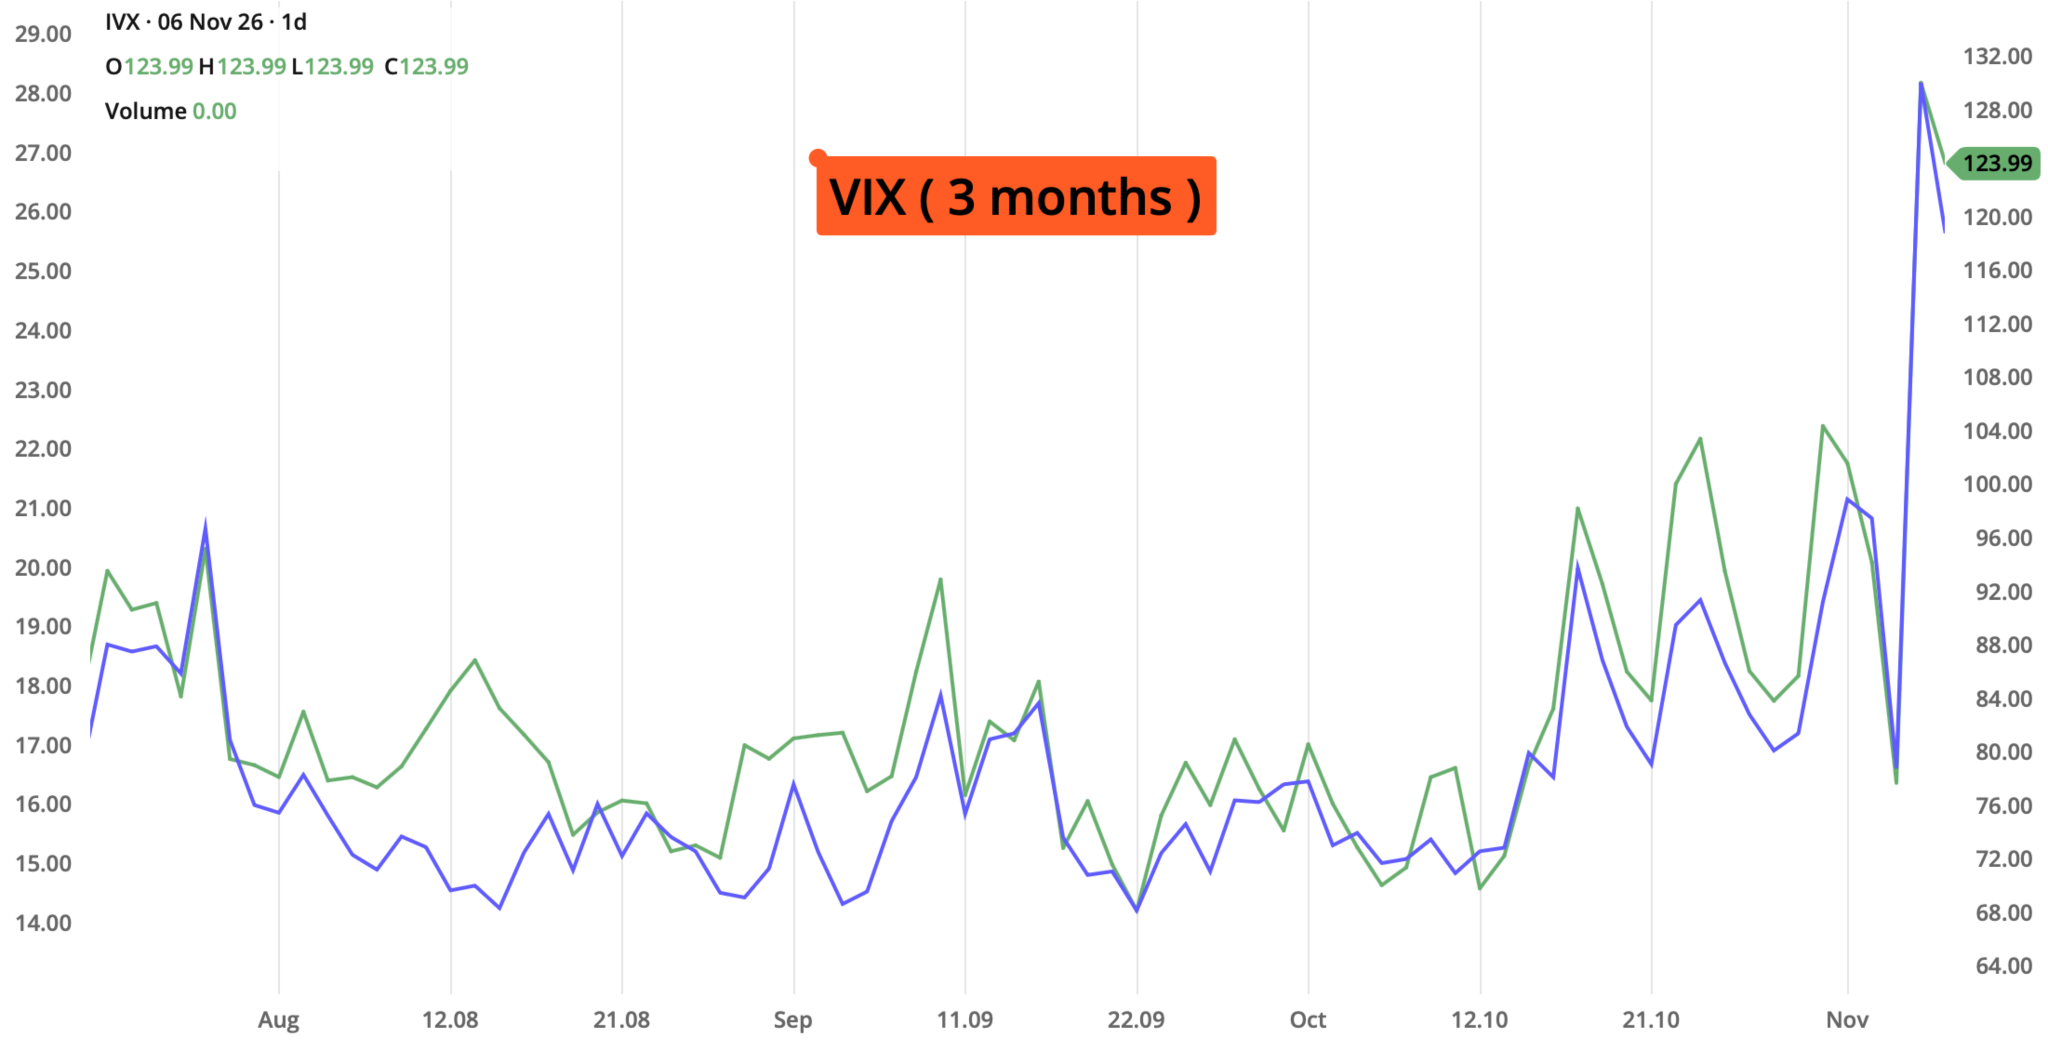
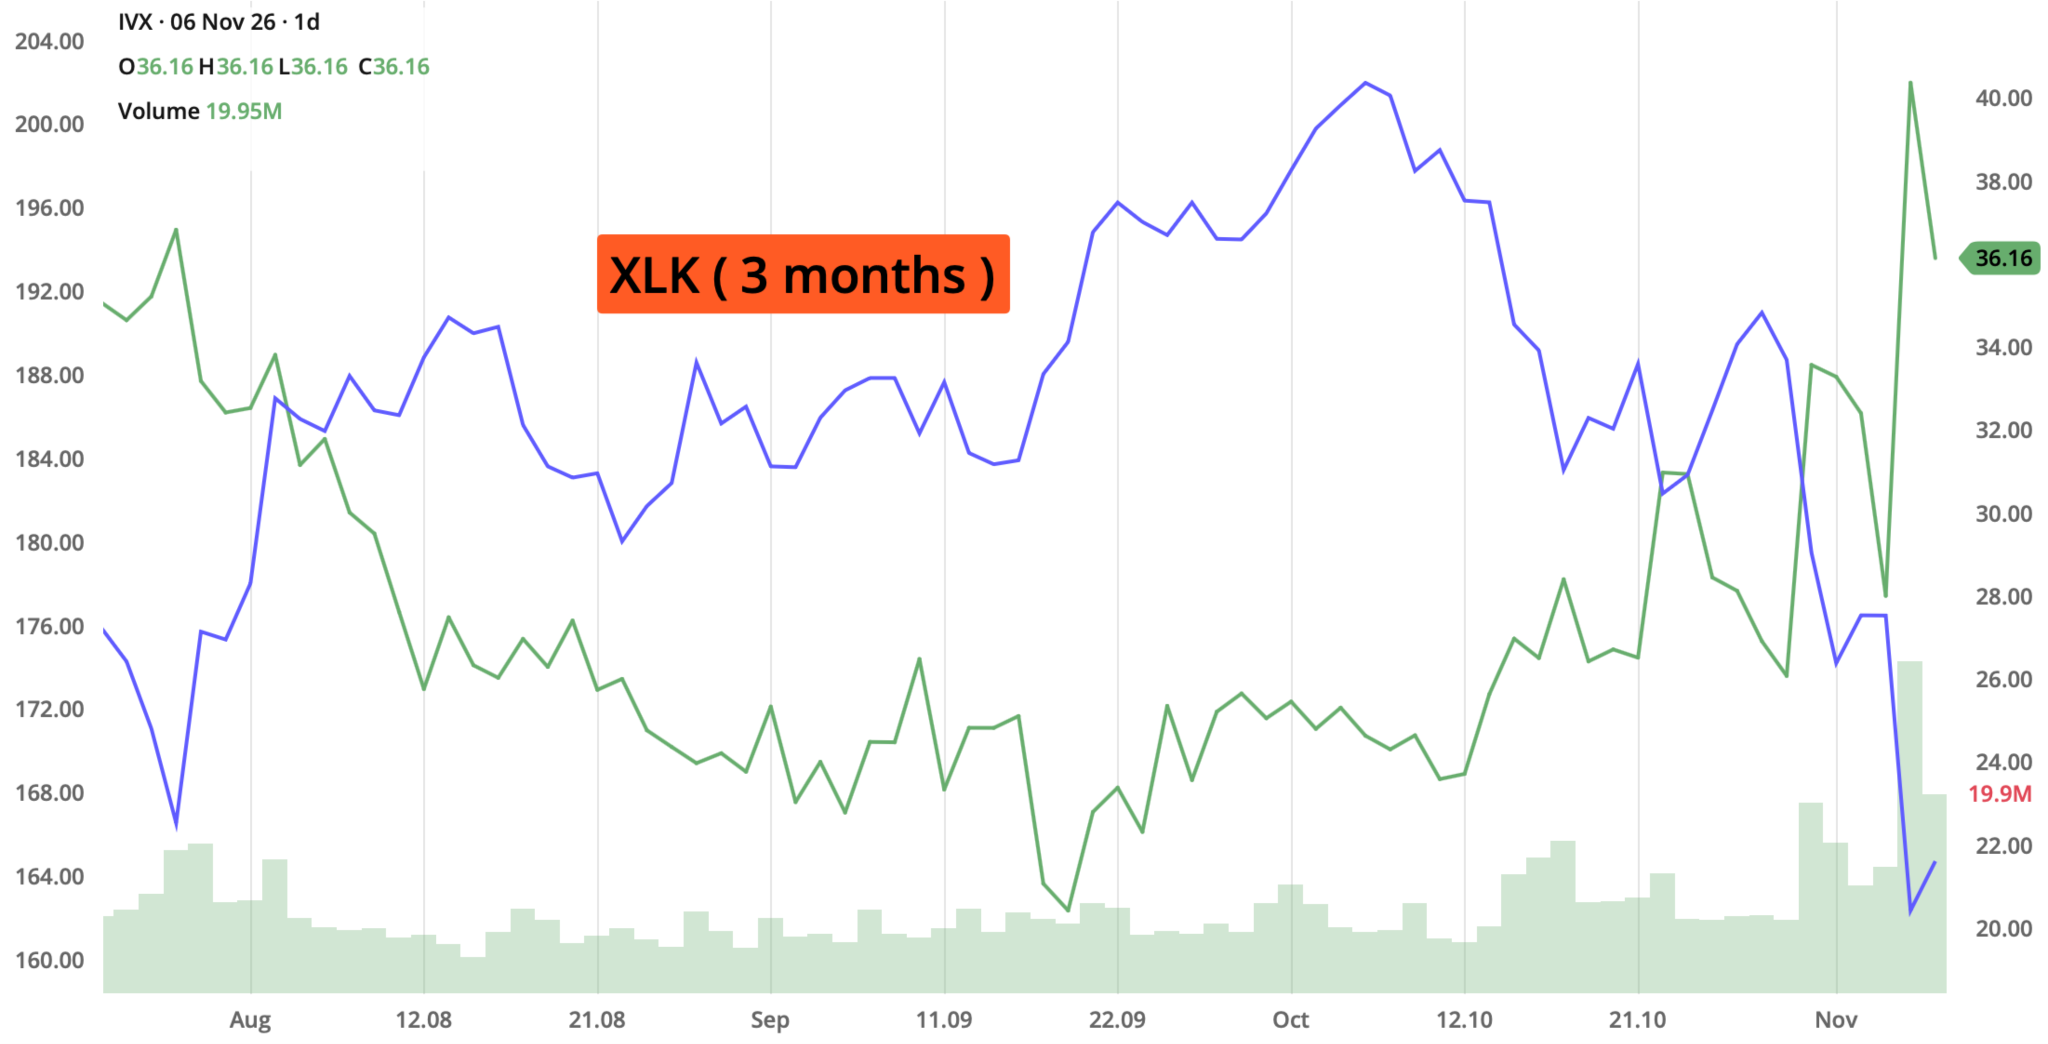
Review selected market indices below:
Daily Notable Market Action
Market Summary for Monday, Nov 2nd
Equities: Stocks started the week under pressure as a pre-election pull-back and profit-taking in mega-cap technology weighed on broader benchmark indices. (S&P 500 Close: 7,541.40)
Bonds: Benchmark Treasury yields caught a mild bid as investors sought shelter in fixed income ahead of the mid-week policy environment. (10-Year Treasury Yield Close: 4.88%)
Oil: WTI Crude oil pulled back sharply following weekend sessions, unwinding recent risk premiums amid demand re-evaluations.(Crude Oil Close: $96.46)
Gold:Spot gold traded higher as defensive hedging provided immediate support against broader equity weakness. (Gold Close: $3,969.60)
Digital Assets: Bitcoin dipped slightly alongside general risk-off sentiment, holding near mid-$78k support levels. (BTC/USD Close: $78,287.79)
Market Summary for Tuesday, Nov 3rd
Equities: Equity markets stabilized into positive territory, carving out a modest rebound driven by defensive sector inflows and short-covering. (S&P 500 Close: 7,568.92)
Bonds: Yields ticked up slightly as economic survey releases signaled ongoing resilience in labor openings.(10-Year Treasury Yield Close: 4.90%)
Oil: Crude prices consolidated in a narrow range as traders evaluated supply-demand imbalances following Monday's drop.(Crude Oil Close: $96.09)
Gold: Bullion edged moderately lower, surrendering minor gains as broader market volatility quieted intraday.(Gold Close: $3,940.40)
Digital Assets: Crypto assets experienced minor selling pressure with Bitcoin sliding beneath $77k. (BTC/USD Close: $76,847.19)
Market Summary for Wednesday, Nov 4th
Equities: Stocks staged a solid midweek rally, propelled by strength across growth sectors and robust ISM services metrics. (S&P 500 Close: 7,688.62)
Bonds: Treasury yields eased moderately following the Treasury's refunding announcement and steady macro prints. (10-Year Treasury Yield Close: 4.85%)
Oil: Crude oil logged a sharp sell-off as inventory builds and global demand concerns drove heavy tactical liquidation. (Crude Oil Close: $88.12)
Gold: Gold surged significantly higher, breaking above key psychological handles on strong safe-haven demand. (Gold Close: $4,073.00)
Digital Assets: Bitcoin saw a modest uptick, tracking the relief rally in equities. (BTC/USD Close: $77,263.81)
Market Summary for Thursday, Nov 5th
Equities: Equities suffered heavy selling pressure, giving back mid-week gains as tech valuation drag and rate jitters re-emerged. (S&P 500 Close: 7,353.73)
Bonds: Bond prices rallied as yields dropped significantly, reflecting flight-to-quality buying amid stock market weakness. (10-Year Treasury Yield Close: 4.84%)
Oil: WTI Crude rebounded off multi-week lows, benefiting from technical dip-buying and localized supply tightening. (Crude Oil Close: $90.52)
Gold: Gold prices extended gains, closing firmly above $4,100 per ounce as risk aversion dominated institutional flows. (Gold Close: $4,113.50)
Digital Assets: Digital assets pulled back in step with broader risk assets, drifting toward $76k. (BTC/USD Close: $75,978.43)
Market Summary for Friday, Nov 6th
Equities: Stocks closed out the week with a modest stabilization, attempting to form a floor after Thursday's sharp sell-off. (S&P 500 Close: 7,376.86)
Bonds: Treasury yields edged slightly higher to close the week following mixed employment data interpretations. (10-Year Treasury Yield Close: 4.86%)
Oil: Energy markets finished quiet, holding key support levels around $90 per barrel. (Crude Oil Close: $90.83)
Gold: Precious metals faced modest profit-taking into the weekend following strong earlier midweek advances. (Gold Close: $4,074.90)
Digital Assets: Bitcoin consolidated near weekly lows, ending the week around $75.7k. (BTC/USD Close: $75,731.04)
Notable Earnings Due for week of Nov 9th–13th
The post-election earnings slate features a broad spectrum of high-volume market leaders spanning technology, energy, consumer services, and global telecom. Early in the week, focus centers on alternative asset management giant KKR, power generator Constellation Energy, and high-volume speculative favorites including Occidental Petroleum and Rocket Lab. Mid-week attention turns to international growth engine Sea Ltd. and Brazilian energy behemoth Petrobras, leading into major late-week semiconductor and hardware reports from Applied Materials and Cisco Systems.
The actual earnings date may vary, so traders should confirm with their brokers. If a trader wishes to open a position to participate in earnings announcements, it is important to check whether the earnings are released BEFORE the markets open or AFTER the markets close on the date of earnings.
Mon, Nov 9th: ASTS / CEG / HIMS / KKR / MNDY / OXY / PLUG / RKLB / TTD / TTWO
Tue, Nov 10th: ALC / CRWV / EC / ONON / PBR / SE / WIX
Wedn, Nov 11th: CAE / CTVA / FNV / RUM
Thu, Nov 12th: AMAT / CSCO / DLO / NBIS / NU / STNE / YETI
Fri, Nov 13th: BRAG / ECC / FSI / MIST / NDLS / OWLT
Economic Calendar Due for week of Nov 9th–13th
The macroeconomic schedule for the week of November 9th–13th pivots from labor market conditions to key inflation metrics, headlined by the October Consumer Price Index (CPI) and Producer Price Index (PPI) reports. Following a stronger-than-expected October jobs report and persistent market sensitivity around central bank policy, these readings will help clarify whether underlying price pressures are continuing to moderate or remaining sticky. With Wednesday's bond market holiday creating a mid-week pause in fixed-income trading, inflation data and wholesale price inputs will take center stage in shaping rate-path expectations leading into December.
Monday, November 9th
- NY Fed 1-Year & 3-Year Inflation Expectations
This regional Fed survey monitors consumer inflation expectations across short- and medium-term horizons. Shifted consumer expectations can influence wage negotiations and spending behavior, making sharp moves up or down a key barometer for underlying inflationary sentiment.
Tuesday, November 10th:
- Consumer Price Index (CPI), Core CPI, & NFIB Small Business Optimism Index
The October CPI report stands as the primary economic catalyst of the week, detailing both headline inflation and underlying core figures. A hotter-than-anticipated core print could elevate Treasury yields and reignite rate-hike concerns, whereas a cooler reading would offer relief to equity markets and support rate-cut expectations.
Wednesday, November 11tht
- U.S. Veterans Day (Bond Market Closed, Stock Markets Open)
With U.S. fixed-income markets closed in observance of Veterans Day while equity exchanges remain open, trading volumes across stock indices may prove lighter than usual. Lower market liquidity during equity hours can occasionally amplify intraday price swings or momentum moves following.
Thursday, November 12th
- Weekly Initial Jobless Claims & Monthly Treasury Statement
Weekly jobless claims offer a timely check on lay-off trends following the monthly employment report. Steady or declining claims would confirm ongoing labor market strength, while a notable spike in new filings would raise fresh questions regarding economic deceleration.
Friday, November 13th
- Producer Price Index (PPI), Core PPI, & Import/Export Prices
The PPI report tracks price changes at the wholesale and producer levels, serving as an important pipeline indicator for future consumer prices. Elevated wholesale price growth or sticky core PPI sub-indexes could pressure corporate profit margins and reinforce broader inflation concerns heading into year-end.
Blue Sky Horizons
The Next Frontier: Physical AI, Humanoid Robotics, and the Industrial Automation Shift
While software-based Generative AI dominated technology investments over the past several years, capital markets are rapidly turning toward Physical AI—the integration of advanced artificial intelligence models, computer vision, and high-precision spatial computing into physical robotics and autonomous machinery. As industrial enterprises transition from digital experimentation to production-scale automation, physical AI is poised to redefine supply chain logistics, high-density manufacturing, and precision assembly.
The structural case for physical AI rests on solving real-world friction: persistent skilled labor shortages across global manufacturing hubs, rising unit labor costs, and the need for higher operational throughput. Unlike early single-purpose industrial robots, modern physical AI platforms leverage real-time spatial world models and dynamic neural networks to adapt to unpredictable factory environments, execute complex spatial tasks, and operate safely alongside human workers. Furthermore, the rapid expansion of edge computing and specialized low-latency processing chips allows these robotic systems to run complex inference models directly on site without relying solely on cloud latency.
For investors looking beyond immediate software copilots, physical AI presents a compelling secular growth narrative at the intersection of capital goods, advanced semiconductors, dynamic motion sensors, and proprietary AI model deployment.
TAKEAWAYS
Self-directed investors looking to gain exposure to the emerging physical AI and advanced robotics supply chain may consider tracking these high-liquidity market leaders for their focus lists:
- NVIDIA Corporation (NVDA): A primary enabler of robotics development through its specialized Jetson edge-AI modules, Omniverse simulation platform (used for training autonomous physical agents), and robotics reference architectures.
- Tesla, Inc. (TSLA): Positioned at the forefront of physical AI scale through its proprietary autonomous driving neural networks and ongoing commercial development of the Optimus humanoid robot.
- Intuitive Surgical, Inc. (ISRG): The clear market leader in high-precision robotic surgery platforms, demonstrating a proven commercial track record of integrating advanced machine vision and robotic execution into medical workflows.
- Rockwell Automation, Inc. (ROK): A pure-play industrial automation and digital transformation provider equipping global manufacturers with the hardware infrastructure, sensor arrays, and software systems required for next-generation factory floors.
- Symbotic Inc. (SYM): An emerging leader in AI-driven, high-speed warehouse and supply chain automation, providing scalable robotics solutions for mega-retailers and logistics networks.
Thank you for reading. Until next week's close,
Have a safe and productive Trading week!
Fauzia Timberlake
About the Author: Fauzia Timberlake is a professional options coach and financial strategist specializing in risk management and portfolio architecture for self-directed investors. She is Founder and Managing Partner of Option Engines.
Questions / Comments
We're here to serve IVolatility users and we welcome your questions or feedback about the option strategies discussed in this newsletter. If there is something you would like us to consider and/or analyze, we're always open to your suggestions. Use support@ivolatility.com.
Previous issues are located under the Trade Ideas tab on our website.